Desire rates across the board have absent up and the financial gain buyers make from a multifamily outweighs a more compact 1-4 device setting up. With costs raising, an trader is better off securing additional units at a increased level, instead than just a solitary-family members expense at an fascination charge at this time previously mentioned 6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. Just just one multifamily investment home can turnaround a struggling, underperforming portfolio. Investors that have skipped out on various qualities throughout past yr can also make up for that decline of opportunity with only a person multifamily property. Desire prices are also tipping the scales toward multifamily investing for the reason that in a market place in which rates are scaring absent anyone, an investor with a multifamily financial investment assets with several models for lease just located by themselves in a high leverage predicament. In an article discovered on wealthmanagement.com, this sentiment is echoed, “As households become more high priced to acquire, and new merchandise a lot more costly to create, the present inventory of rental housing results in being extra important and in-need.”
Multifamily financial investment qualities are essential for a selection of explanations but mostly for investors the most beautiful factor is the scalability chance it results in for them. The funds generated from a rental house, occasionally referred to as passive income, is amplified tremendously by possessing a multifamily property. With this money coming in due to quantity of units, it is less difficult for traders to extend and make down payments on investments. Any investor will acquire you as a result of their journey that typically commences with modest resolve and flip initiatives, shifts to owing solitary family rentals and jumps to owning multifamily properties. Buyers are normally wanting for the following problem and a probability to receive the greatest ROI. With multifamily financial commitment properties, the route to financial liberty has under no circumstances been a lot easier. With a companion or two and a several trusted property professionals, traders can cross the 50–100-unit threshold with ease.
Liquidity equals flexibility
Liquidity is a further beautiful reason why buyers want multifamily expense qualities in their portfolio. As opposed to stocks and bonds, a multifamily expense residence holds its worth at a significantly extra reputable price than an expenditure in the stock sector. That value will make these investment decision homes significantly far more captivating and offers flexibility to an financial investment portfolio. If a new house arrives on the sector and an investor needs to liquidate before long to totally free up some cash to make a down payment, a multifamily investment is just the asset they would need to have. Whether it is marketing off a selected selection of units to make it worthwhile or unloading the multifamily house fully, an trader can come up with that down payment money. Inventory sector situations could lead to an investor to miss out on an possibility if the market place is down, so having that multifamily home can demonstrate to be considerably a lot more reputable.
Part 1 focused on “Home Stocks,” meaning those that I would be happy to buy now and hold indefinitely, like a home. They were Brookfield Corporation (BN), Brookfield Asset Management (BAM), Dream Unlimited Corp. (DRM)(OTCPK:DRUNF), Topicus (OTCPK:TOITF), and SSC Security Services Corp. (SECU)(OTCQX:SECUF). These are stocks commonly referred to as “compounders,” meaning they grow reliably, profitably, and over long periods of time. If the stock market were to close for ten years, Home Stocks I would not worry about.
Like those stocks, “Investment Property Stocks” are growing profitably, but have some sort of drawback and that make them less attractive over the long term. This drawback is made up for by a large, temporary dislocation between price and value, providing an attractive risk/reward that could result in a large return over a relatively short period, anywhere from one to five years. When the stock’s price gets close to its value, I’ll consider selling for a nice gain. Thus, they are Investment Property Stocks, not Home Stocks.
Currently, I find Nuvei Corp. (NVEI), a Canadian mid-sized e-commerce payments company, Alibaba (BABA), China’s pre-eminent internet stock, and Reitmans (RET)(RET.A)(OTCPK:RTMAF), a Canadian women’s fashion retailer, to be attractive Investment Property Stocks. All have something going against them which dissuades me from holding over the long term, but enough going for them and a large enough margin of safety that I believe they can make very nice gains in the next one to five years.
Investment Property Stocks
Nuvei Corp.
Nuvei Corp. is a mid-size Canadian fintech (~$4-5B market-cap) specializing in merchant services; it essentially has a top-of-the-line modular “everything platform” for merchants. I go into greater detail here but a shorter version follows.
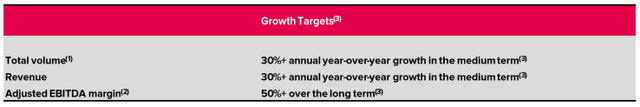
Nuvei specializes in payment solutions for online regulated gaming (gambling and sports betting), a fast-growing segment as Canadian provinces and US states legalize the industry, and e-commerce generally, which represents almost 90{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of their revenue. Nuvei is quickly diversifying however, most recently they acquired Paya Payments, a B2B payments provider, the details of which I cover here. In addition, the CEO owns 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of shares, and upon its IPO employees each received a stake in the company worth $100,000, creating significant insider-ownership. Management projects sales to grow at 30{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} annually over the next few years with adjusted EBITDA margins increasing up to 40-50{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, a call that was recently reiterated in a press release. Nuvei has competitive technology, huge growth in sales and margins, and owner-operators; it meets my normal qualifications of a quality stock.
Nuvei’s growth outlook (Nuvei’s Q3 Earnings Report)
Despite these positives, Nuvei trades at 11x trailing free cash flow. The reasons for this are not perfectly clear, but here are a few possibilities.
Payments companies generally are down huge due to recession fears caused by interest rate hikes and inflation. Companies operating in cyclical sectors like e-commerce and online gaming are even more affected. Nuvei was also exposed to crypto payments, which crashed hard in 2021, bringing Nuvei’s share price with it. The exposure is not huge, but the mere association was enough to hurt the stock.
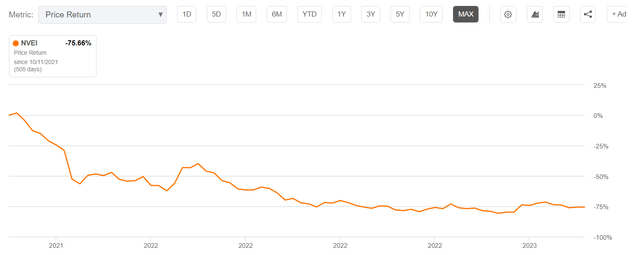
Additionally, Nuvei was one of the prime beneficiaries on the pandemic bubble, a lot of its growth was brought forward, and its share price skyrocketed beyond what anybody could consider reasonable, and thus became the target of a short seller’s report. Many of the allegations were rebutted, but the share price didn’t recover. More concerning is the CEO’s relative youth, reflected in how much he pays himself (a lot), and that Nuvei pays presumably large amounts to sponsor an F1 team. I fail to see how such a sponsorship benefits shareholders, but doesn’t break my thesis on the company, though it is inconvenient.
Nuvei’s return since its IPS – Not pretty! (Seeking Alpha)
Lastly, bringing forward growth also had the effect of creating impossible comps year over year, indeed Nuvei’s sales this year are up only single digits over last year. Considering they doubled sales in 2021, simple staying flat is quite the feat, and puts management’s forecasted 30{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} medium-term sales growth seem far less ambitious than it appears. It also probably didn’t help that they converted their net cash position to a net debt position to acquire a company; it isn’t the market for that. Overall, I view most of these factors as temporary impairments to the stock, and therefore signify a potential opportunity.
Most importantly for me, and why this stock is not a long-term hold, is competition. In the payment services world, a company is only as good as its technology developers and sales team; there is no moat, or even picket fence, keeping others out of the business castle. Nuvei’s peers are Stripe (STRIP), Block (SQ), Europe-based Adyen (OTCPK:ADYEY) and to a lesser extent online payments companies like PayPal (PYPL). All are worth 10s of billions and with significant resources; competition is clearly formidable.
That said, Nuvei is currently much smaller than they are so need to take less market share to see gains, has competitive technology, is building a direct sales team with a former Mastercard exec at its head, has a niche and early movers advantage in online gaming payments, and is priced for the apocalypse, while its competitors are priced for a recession. The lack of durable competitive advantage is made up for by these redeeming factors, but especially by valuation.
A cursory glance at the stock suggests it is expensive because it has a high PE ratio, but if we skip to the cash flow statement, we see that Nuvei gushes free cash flow. Gross margin is above 80{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, operating cash flow margin is regularly above 40{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and free cash flow around 35{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. Due to operating leverage, where little capital is required to provide more services, margins even have room for expansion. These are levels are profitability beyond even Microsoft.
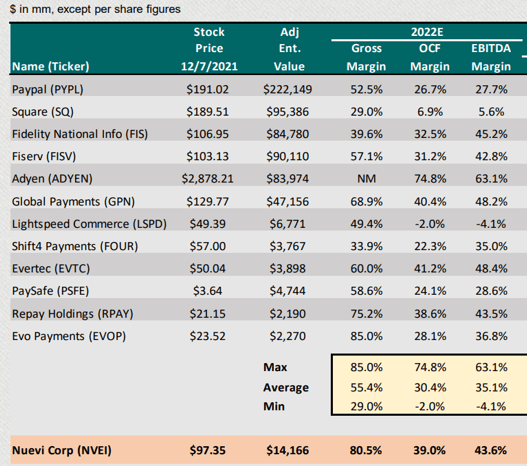
To be honest, my “too-good-to-be-true” sense is tingling, and I’m not the only one. In the short seller’s report, they made a list of comparable fintechs and their profitability. Most of the report was, from my perspective, ad hominem hearsay, but the following breakdown was useful:
Note to Canadian investors, Lightspeed gets more press than Nuvei, but isn’t even profitable. (Short Seller’s Report)
A close look will reveal that Nuvei is about as profitable as a fintech can be and far above average. This could be concerning, but comfortingly for me, there are other companies that are similarly profitable so Nuvei is not a clear outlier. Adyen for example, its closest peer, has operating cash flow and EBITDA margins much higher. This chart is useful for industry comparisons as well, which I’ll leave to the reader to peruse. In my opinion, the probability that Nuvei is cooking the books is low, though I am wary.
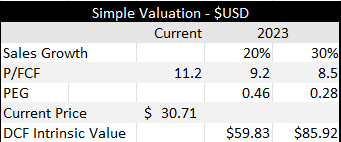
Nuvei is tremendously profitable, and, as the table below shows, the market is strongly discounting this fact, assigning it an 8-9x forward P/FCF multiple, half the average of information technology stocks according to Seeking Alpha. Nuvei should perhaps demand even more than average as it is a quickly growing fintech stock with huge margins and operating leverage.
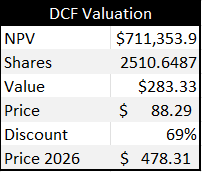
Two different growth scenarios and their impact on the valuation of Nuvei. Both suggest Nuvei is substantially undervalued (Author’s Calculations)
As we can see, the stock is at least 50{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} discounted from conservative fair value, assuming management’s medium-term outlook of 30{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} annual sales growth is high by 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} a year. If it’s not, and Nuvei does manage to grow sales at 30{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} annually while maintaining or growing current margins, the stock is potentially 66{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} undervalued. Furthermore, a PEG ratio of 1 is generally considered a fair price to pay, and Nuvei trades at half or a quarter of that, lending further support to our DCF values. Should the market get bullish and payment stocks demand higher multiples (the current model assumes 20), upside is even greater.
Nuvei is certainly not a Home Stock, in that it doesn’t have a moat and there are some smaller concerns, but the price and business model are far too discounted; a disaster is being priced in. If business doesn’t flop and/or the Great Depression doesn’t happen, Nuvei is going upwards. The main catalyst is lapping 2021’s financials making for easier comps, and new customer wins.
I’m a buyer at $30-$35 USD and would consider selling at $90-$120, though I wouldn’t make this an out-sized position as the company hasn’t been public long so it’s hard to get a sense of its track record.
Alibaba (BABA)
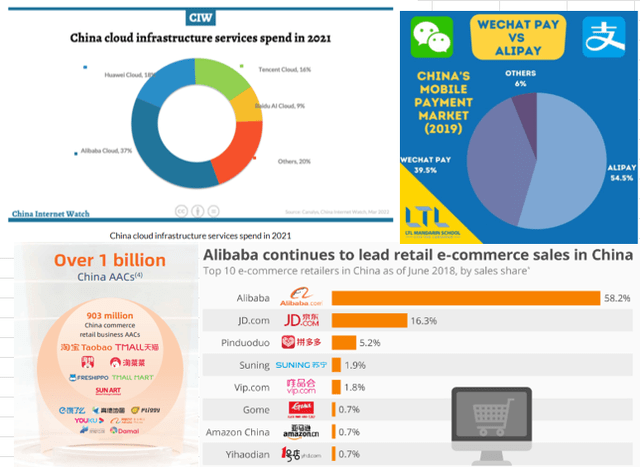
Alibaba is the pre-eminent Chinese internet stock. 60{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of Chinese e-commerce goes through one of its platforms, 37{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the fast growing cloud market is captured by Alibaba, almost every single Chinese person (and 300M outside China) are annual active consumers on its platforms, and, through its one third stake in Ant Financial, BABA owns Alipay, the payment platform through which 56{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of Chinese payments flow (with more volume than Visa, Mastercard and Amex combined) and Yu’e Bao, the second largest money-market fund in the world with over $170B under management. Alibaba has an ocean for a moat.
In addition, they have fast growing segments, like international e-commerce and domestic groceries, both of which alone could be bringing in more annual sales by 2033 than the entirety of Alibaba generated in the last twelve months. Alibaba is more than just the Microsoft (MSFT) or Apple (AAPL) or Amazon (AMZN) of China, it’s all of them, combined.
Visuals to aid readers in understanding Alibaba’s moat (China Internet Watch, Mandarin School, Alibaba 2022 Annual report)
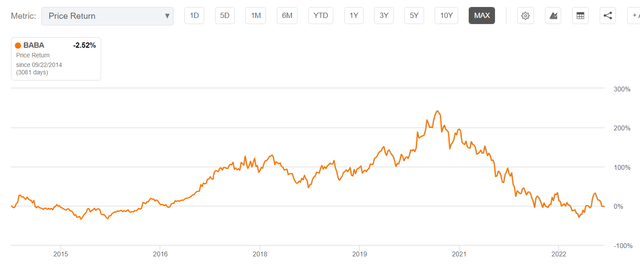
Since it IPO’d in 2014 at $92.70 a share, Alibaba has 15x the revenue, 5x the EBITDA, 4.5x the free cash flow, and 3.5x the operating income. Somehow, we can buy it at IPO prices; Alibaba is tremendously undervalued. Tom Hayes describes it as a submerged balloon, waiting to rocket to the surface.
Alibaba’s return since its IPO (Seeking Alpha)
The dislocation of price to value is caused by the Chinese government locking down the economy in an attempt to prevent Covid from spreading and cracking down on its tech companies, which it deemed were becoming too powerful (perhaps justifiably). Things have changed recently however, the CCP bought shares in BABA, has re-opened the economy, is stimulating the consumer, and generally seems to be working with and through its tech companies as China’s leaders’ personal and national self-preservation instinct has kicked in. Headwinds have shifted to tailwinds.
I’m putting up my sails to catch that wind, as Alibaba, were it to return to normalized multiples on normalized earnings, is worth at least $500-$600 a share three years from now. This plan appears to be on track. In their most recent earnings, Alibaba bought back significant amounts of stock well below intrinsic value, somehow grew revenue 2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} despite the most recent quarter being under lockdown, and, significantly, increased free cash flow 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} year over year despite sales staying flat. This means that Alibaba found a way to become much more profitable in a very short amount of time. Once sales growth starts to kick back in, combined with increased profitability, BABA shareholders could see results well beyond normalized earnings, and therefore have much more upside.
Valuation of Alibaba assuming its free cash flow margins and multiples paid for that FCF returns to historic averages (Author’s Calculation)
Moreover, Chinese savings are twice the historic average, so if they can spend at normal levels, upside could be even higher, considering the market currently expects a conservative 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} annual growth of sales over the next few years for BABA. Shareholders of Alibaba have a significant margin of safety at current prices, and massive upside should anything go right.
I’m an active buyer and will continue to accumulate under $100 a share for as long as the market lets me. I’ll consider selling when it reaches that $500-$600 mark but will reassess when we get there. If international expansion is going well, BABA might turn into a long-term hold.
I did a longer article on Alibaba here.
Reitmans (OTCPK:RTMAF)(RET.A:CA)(RET:CA)
Reitmans is a century-old Canadian women’s fashion retailer, including the brand’s Reitmans, Pennington’s, and RW & Co. The Reitmans family still owns most voting shares (RET:CA), and senior management positions. Donville-Kent, a Canadian small-cap investing firm whose newsletter, the ROE Reporter, alerted me to the opportunity here. Their treatment is in-depth and can be read here.
Reitmans historically was a reliable dividend payer with sluggish growth in the Canadian retail space, like Canadian Tire in this respect. After years of deterioration however, Reitmans almost didn’t survive the pandemic and was forced to enter bankruptcy to survive. In so doing they laid off thousands of employees, renegotiated better lease terms, paid off creditors at 50{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} on the dollar, shut down unprofitable locations and brands, and re-listed from the TSX to the TSXV.
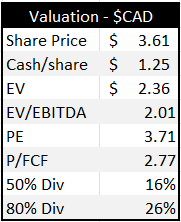
Re-emerging from bankruptcy, the company looks remarkably different, financially. Returns on equity are over 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, debt is paid off and they have $1.25 of cash/share (a quarter of the company’s market cap is cash). In the last nine months alone, Reitmans has generated $67M in free cash flow on $588M of sales, for a margin of 11{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, an excellent number for a retailer. Using just the last nine months numbers, they currently trade at around 2x EV/EBITDA, 4x net income and 3x free cash flow, well below historical averages for their own company specifically and retail generally.
Remarkably undervalued. Priced like it’s going bankrupt again (Author’s Calculations)
If Reitmans were to pay out 50{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 80{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of that free cash flow as a dividend (which they have historically), the stock would yield 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. If that isn’t enough, the headquarters and distribution centre owned by Reitmans are worth more than the market cap of the company. The value is clear.
Like BABA, there is a large overhang on the stock causing its price to be severely depressed, but the facts are pointing to this overhang being temporary.
The new Reitmans could continue to be the dog it was in the 2010s, but if its last fiscal year is anything to go by, this doesn’t appear to be the case. Indeed, the current overhang from bankruptcy and Reitmans reputation is providing a margin of safety and likely an opportunity. Shareholders will need catalysts to continue gains though.
Reitmans has several potential catalysts. First, the company could buy back a significant amount of stock with just the cash on the balance sheet. Second, it could reinstate the dividend, which I’m sure the Reitman family are eager to do as it’s been a few years since they got the cheque they’ve been receiving for almost a century. Third, they could list back onto the TSX proper, where fund managers can buy their stock. Fourth, the family could buy the land under their headquarters and fulfilment centre and lease it back to the company, unlocking a pile of cash. Fifth, when earnings are reported in April, we get our first full year of financials for the new Reitmans, and potential announcements regarding any of the first four points made here. Reitmans is already up significantly, but there are more catalysts that could cause it to go even higher.
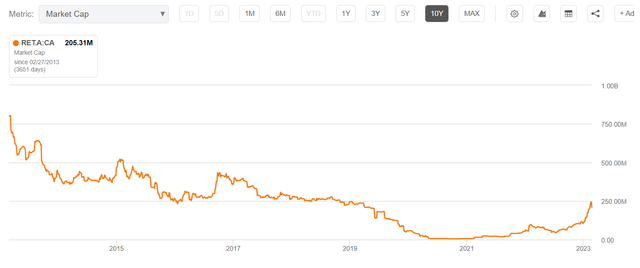
Long-term holder are likely non-existent (Seeking Alpha)
Over the last 10 years, Reitmans was a value trap, with slowing sales and decreasing margins and thus traded at very low multiples, around 7-8x free cash flow (which is still twice as expensive as today). However, sales are not slowing anymore, its brands are proving resilient, and margins have expanded significantly coming out of bankruptcy. 8-10x EV/EBITDA and/or 8-10x FCF are perhaps more appropriate conservative expectations of multiples going forward, compared to the current 2.3x EV/EBITDA and 3x FCF. This suggests that Reitmans is likely a double from ~$3.50-$4.00 on valuation alone, with more potential should the catalysts mentioned earlier happen. Donville-Kent expects the price to reach around $8 if the company doesn’t sell the land to the family, and $12 if they do.
If the outlook remains rosy, the company proves quality and the dividend is reinstated, I might find myself a long-term holder. To put it in perspective, with an 80{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} payout ratio, I’ll be receiving upwards of 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} yield on my current cost-basis; a 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} annual cash return is hard to say no to. This should result in price upside as well, as 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} yield from a quality company will not last long; I could see a more justifiable yield of around 6-8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, implying the price could increase another two or three times, like Donville-Kent suggested.
In any case, I see a double minimum with potential for RET.A to triple or quadruple, while I eventually collect a significant dividend yield that I could choose to hold for the longer term. Reitmans is an ideal Investment Property Stock.
Conclusion
Reitmans, Alibaba, and Nuvei are all promising stocks into the medium-term. Though they have long-term drawbacks, namely low growth at Reitmans, ageing demographics and an autocratic home government for Alibaba, and no durable competitive advantage for Nuvei, the market is pricing their stocks at unreasonably low levels. To re-value their stocks, Reitmans could reinstate the dividend and go back up to the TSX, Alibaba could benefit hugely from government stimulus and domestic cloud growth, and Nuvei will be lapping tough 2021 financials, leading to some pleasing year of year numbers. All are quality businesses down for temporary reasons, and have catalysts to revive investor interest.
If worst-case scenarios don’t happen, all these stocks could be doubles in a relatively short period (a couple years or less), and perhaps more into the medium-term (3-5 years). I’m in all of them at allocations I feel are appropriate and am excited to see what the future brings. I would love to become a long-term holder but will reassess later. For now, these make for great Investment Property Stocks.
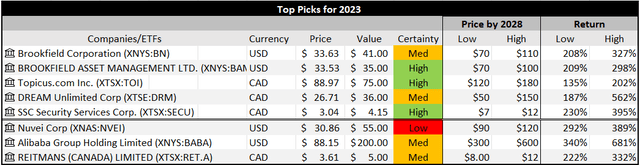
Below is a final summary for all the Top Picks for 2023:
Summary of top picks in the last two articles, including fair values and return potential (Author’s Calculation)
Please feel free to comment, especially dissenting thoughts.
Editor’s Note: This article discusses one or more securities that do not trade on a major U.S. exchange. Please be aware of the risks associated with these stocks.
Thinking of investing in real estate? Before acquiring an expense residence, you want to make positive that it will generate at least more than enough funds to address your monthly carrying charges — and, ideally, extra. Which is where the 1 {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} rule will come into play. This true estate rule of thumb can help investors determine irrespective of whether a specific home will be worthwhile for them, centered on its acquire price tag and every month rent. Here’s how it works.
What is the 1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} rule in serious estate?
The 1 p.c rule is a true estate investment guideline that allows traders immediately estimate the minimal month to month lease they have to cost to break even (at minimal) on a particular home. Exclusively, the rule indicates that the rent on an financial investment assets need to be equivalent to or greater than 1 {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the property’s sale rate.
Here’s another way of seeking at it: When viewing possible rental attributes, buyers can use the 1 percent rule to assist choose no matter whether the purchase price is worthy of the profits it is probable to create.
It is crucial to mention that the 1 {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} rule is merely a guideline, not a tricky-and-quickly rule. It doesn’t take into account all the variables that could influence no matter if or not a opportunity assets is really worth the investment decision at the time. It is a practical (albeit imperfect) shortcut to calculate the approximate amount you’ll need to have to cost in monthly rent in purchase to make a earnings.
How it is effective and how to estimate it
To work out regular monthly rent employing the 1 per cent rule, just multiply the home’s obtain price tag by 1 p.c. If repairs are essential, incorporate the repair service fees in with the buy price tag.
Calculator
Order Price tag (Together with Fix Charges) x .01 = Least Month to month Hire
For illustration, let’s say you are looking at a duplex household outlined at $250,000 which is in great problem and doesn’t need any instant repairs. Employing the 1 {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} rule, you’d need to have to bring in at minimum $2,500 for every month complete, or $1,250 for every unit, to address your fees.
Now, let’s say you’re wanting at a $150,000 single-family members residence that demands $25,000 well worth of repairs. In that case, you would multiply $175,000 by 1 {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to get a minimal regular hire of $1,750.
You can also apply the 1 per cent rule to gauge no matter if or not a home may be a great financial commitment based on its historic hire. For instance, if a household is shown for $200,000 and the most latest tenants paid $1,500 for each thirty day period, which is a lot less than 1 per cent — and, as a result, most likely not an interesting expense. But if the tenants were being shelling out $2,500 for each month, the property would move the 1 percent rule.
What it doesn’t take into account
There are some limits to the 1 p.c rule. For case in point, although it does component in any original repairs that the property needs, it does not contemplate the ongoing expenditures of homeownership. House entrepreneurs normally bundle these costs into their tenants’ lease, but if you use the 1 {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} rule, these expenses will not be reflected in the every month hire full.
Property finance loan fees
The every month value of a house loan depends, of study course, on the mortgage’s interest price. The same $200,000 residence might be a superior expenditure at 5 percent but not so a lot at, say 6.5 per cent. Be confident to variable in your bank loan terms and what your every month property finance loan payment will be right before investing in any residence.
Routine maintenance and repairs
As a home owner, you’ll have ongoing upkeep expenditures like garden treatment, HVAC upkeep and pest handle. Some of these expenses can be unpredictable, which can make it complicated to prepare for them, so budget correctly.
Property taxes and insurance coverage premiums
You are dependable for shelling out your home’s once-a-year assets taxes, which change extensively by state and municipality. The median property tax bill in the U.S. is $2,375, according to World Population Overview. In addition, you’ll have to have to invest in coverage for your residence — especially landlord insurance, which is generally much more pricey than normal property owners insurance.
Property owners affiliation charges
If the property is in a community managed by an HOA, you’ll will need to pay out standard dues. These can variety very a little bit relying on the features and products and services available, so make certain you know accurately how significantly you will have to tack on to your every month expenses to protect them.
Atypical markets
The 1 p.c rule might not apply in specifically dear marketplaces, like San Francisco and New York Metropolis. For case in point, the median sale rate of a house in San Francisco was $1,385,000 in January 2023, according to the California Association of Realtors. Working with the 1 percent rule, you’d require to cost more than $13,800 per month in lease just to split even, which is simply just unrealistic for most rental homes.
Other authentic estate principles to know
There are quite a few common real estate tips centered on percentages. In this article are a few some others that might be useful:
The 2 per cent rule: The same plan as the 1 per cent rule, just a little bit stricter. It suggests that any residence ought to make at the very least 2 {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of its order rate in every month hire.
The 28 {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} rule: This guideline recommends that you commit, at most, 28 p.c of your gross month-to-month money on your home loan payment. A lot of loan providers think about this when examining your software.
The 70 {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} rule: The 70 per cent rule assists home flippers identify how much they can expend on a house centered on its following-mend price (ARV) — the home’s expected value right after renovations are comprehensive.
Base line
If you’re in the early stages of assessing rental qualities to commit in, the 1 p.c rule is a speedy and quick way to estimate the minimum sum you’d have to cost in hire to make a earnings. Hold in thoughts, nonetheless, that it is just a common rule of thumb, so you shouldn’t depend on it to offer a specific determine.
Soon after 40 years of sitting in website traffic and punching the clock, you will sit and punch no far more. When your property was fantastic for elevating a relatives and earning a residing, you have made a decision to relocate in retirement. But you may possibly be inquiring you, really should I sell or rent my house? This decision is complicated since there are investment, tax and non-money issues. We will address them in that order.
Is Your Dwelling Considered a Good Financial investment?
Your household as you have utilized it throughout your working yrs, is just that, a dwelling. You have to consider it as a home 1st, financial commitment second. If you are taking into consideration renting out your property, that order reverses. I typically speak with customers who argue that they should retain the residence simply because the lease is adequate to cover the house loan price tag, or that, simply because there is no house loan, this is great “passive income.” These are not superior methods to assess the excellent of the expenditure. Under are a couple of procedures of thumb:
The 1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} rule. You must be ready to get 1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the present-day invest in price of a residence in regular hire. But what if there is no obtain price tag? You previously very own the house. I think that if you are approaching this objectively, you have to check with yourself: Would you buy this residence for the present value, as an financial commitment?
Subscribe to Kiplinger’s Particular Finance
Be a smarter, much better educated trader.
Save up to 74{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
Indication up for Kiplinger’s No cost E-Newsletters
Financial gain and prosper with the very best of qualified assistance on investing, taxes, retirement, private finance and additional – straight to your e-mail.
Income and prosper with the finest of skilled advice – straight to your e-mail.
For illustration, if a dwelling is well worth $750,000, you should really be ready to get $7,500 per month in lease. You may perhaps be wondering, “No way!” And, if you are living in a superior price-of-residing space, you are almost certainly proper. It is unlikely you’ll get that much. As an alternative, in these marketplaces, you are normally betting on home appreciation.
Some would argue that, with the run-up in prices above the final many yrs, the 1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} rule is now far too high. I imagine of it in the exact same vein as the 4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} rule for retirement distributions. In certain environments, it could be way too substantial or too small, but it is a great rule of thumb to at least figure out if you’re in variety of the target.
Cap fees. Cap costs are the actual estate term for yield. You choose your total revenue, considerably less running bills, and divide that by the house price.
For case in point, say you have a $750,000 property with $6,000 per thirty day period in hire and $2,000 for every thirty day period in charges. Your cap level is $48,000 divided by $750,000, or 6.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. The complete return of the financial commitment is the yield furthermore any anticipated appreciation.
Liquidity. Liquidity has to be a thought, simply because as opposed to shares and bonds, actual estate is a great deal a lot less liquid. In certain markets, like the spring of 2021, true estate is uncomplicated to sell. The current market in 2023, not so much.
Tax Concerns for Offering and Rental Home Money
There are considerable tax advantages of offering a most important residence. So lengthy as you have lived in a property for two of the previous five several years, you are entitled to the 121 exclusion (opens in new tab). This will allow for you to exclude up to $250,000 of capital gains. If you’re a married couple residing in the home, it is $500,000.
If you are thinking of turning your dwelling into a rental, it is feasible you are going to reduce that exclusion if you hire the residence out for extra than 5 yrs.
If you convert your residence into a rental house, you have to consider how cash flow will be taxed. As a standard rule, earnings from genuine estate is taxed as earnings instead than (typically a lot more favorable) cash gains.
However, there is preferential tax procedure in that most expenditures of the residence are deductible, and the dwelling value can be depreciated about time. Rental cash flow and charges are proven on a Schedule E (opens in new tab). Whilst the kind alone is not intricate, owning a rental home will complicate your tax predicament and could call for hiring a CPA or an enrolled agent (EA) (opens in new tab).
Non-Economic: Rental Home Isn’t Seriously ‘Passive’ Earnings
Consider the infamous three T’s: trash, toilets and tenants. Without them, currently being a landlord would be a breeze. It would also occur with no monetary advantage. To deal with this kind of challenges, you can retain the services of a house manager — and if you go out of town, you probably should really. But that will eat into all those cap prices.
The most important grievance we hear from our shoppers who personal rental attributes has very little to do with their ROI it is that they are generally on call. I’m guessing that’s not how you want to invest your golden many years.
And finally, what if it is feasible you’ll shift again? This is a massive argument in favor of hanging on to your dwelling. Transaction expenditures are so high in the genuine estate earth that you do not want to be in a problem the place you really don’t like your new locale, opt for to shift back again and have to buy a new area.
I know that there was no clear tips here on what to do. Somewhat, you now have a list of the large issues you really should look at.
I will stop on this: Dabbling in the financial commitment assets business enterprise is unsafe. The actual industry experts do this for a dwelling and can make a great deal of funds, usually for the reason that of the leverage (loans) included. I propose in opposition to dabbling.
This post was prepared by and presents the views of our contributing adviser, not the Kiplinger editorial staff. You can check adviser information with the SEC (opens in new tab) or with FINRA (opens in new tab).
North Texas Residence Administration is very pleased to announce new articles aiding buyers fully grasp the positive aspects of qualified administration services.
FRISCO, TX, February 26, 2023 /24-7PressRelease/ — North Texas Residence Administration, a ideal-in-class financial investment property management business based in Plano, Texas, and serving Collin County is proud to announce new informational information targeted on the key communities of Richardson, Allen, and Plano, Texas. One family members property home investors could need to have the assistance of a regional qualified to juggle the everyday facts essential for handling rentals.
“Big assets investors can evidently realize the duties of handling financial commitment rentals in Texas. More compact traders, both these new to the rental industry or those people who have inherited a house and want to lease it out, may not realize all the ins and outs of residence administration,” explained Jason Marascio, North Texas Assets Management CEO. “We do and we can assistance them by having more than every day and every month perform necessary to thoroughly handle a property rental. We are only centered on the house management of financial investment properties.”
The new informational submit can be located at https://www.ntxpm.com/2023/01/14/when-you-need-expenditure-assets-management-employ the service of-the-best/. Little traders searching for facts on financial investment house administration in Richardson, Allen, and Plano, Texas, can study solutions in the new submit as effectively as on location-distinct pages these kinds of as https://www.ntxpm.com/richardson/. NTXPM can support entrepreneurs of one-family members dwelling rentals. The local rental administration staff can deal with duties these kinds of as the following: advertising and marketing a household for rent, residence inspections, scheduling tenant interviews, running renter background checks, and even eviction companies (https://www.ntxpm.com/eviction-company/). The firm’s workers can gather lease, agenda household repairs and offer a monthly economic statement to the assets investor.
The Most effective Financial investment Home Management Services Presents Hassle-cost-free Aid
Listed here is the track record on this release. Lots of newbie traders may well be tempted to “go it alone” when it will come to investment decision assets management. This could not, having said that, be the most effective decision. Utilizing a residence administration service for a single family members household rental home can present numerous benefits in excess of taking care of the property oneself. House management corporations can deliver a range of solutions, including marketing the assets to future tenants, screening tenants, gathering lease, handling maintenance and repairs, and implementing lease agreements. These services can help save residence house owners time and exertion and can guarantee that the house is very well-taken care of and in compliance with community polices. Residence management corporations in Plano and close by communities also have experience in the nearby rental market place, letting them to set competitive rental charges and industry the home proficiently. Additionally, residence administration organizations can provide a buffer in between the assets operator and the tenant, dealing with any disputes or conflicts that may arise and cutting down the anxiety and workload for the home operator.
ABOUT NORTH TEXAS Residence Administration
North Texas House Management Business is a top rated-rated home administration firm servicing rental residence owners’ desires in the North Dallas spot of North Texas. The firm’s residence professionals manage residential rental homes in McKinney, Richardson, and Allen, Texas. NTXPM also handles single-loved ones house property administration for Frisco, Plano, Carrollton, Garland, and Princeton, Texas. The team supports each the wants of renters and landlords in the North Dallas suburbs.

If you might be a rental residence proprietor, you know that preventative upkeep is critical to retaining your tenants satisfied and your financial investment in great shape. But what just falls beneath the umbrella of preventive servicing, and why is it so vital? Retain examining to discover the response to these thoughts and far more!
What is Preventative Maintenance
Preventative servicing could audio like a extravagant way of saying “housekeeping,” but it is substantially additional important than that. Preventative care includes examining for possible troubles, making sure methods functionality accurately, and even executing process updates. It is effectively having a proactive technique to maintaining the house you rent out. As a rental property operator, retaining up with preventative maintenance will assist you help save income and problems in the very long run. Imagine all the significant repairs you can keep away from and the subsequent peace of head it would deliver! When it arrives to becoming a effective landlord, preventative upkeep is important: get in advance of troubles before they get started. 

 HVACs, Air Filters, and Dryer Vents
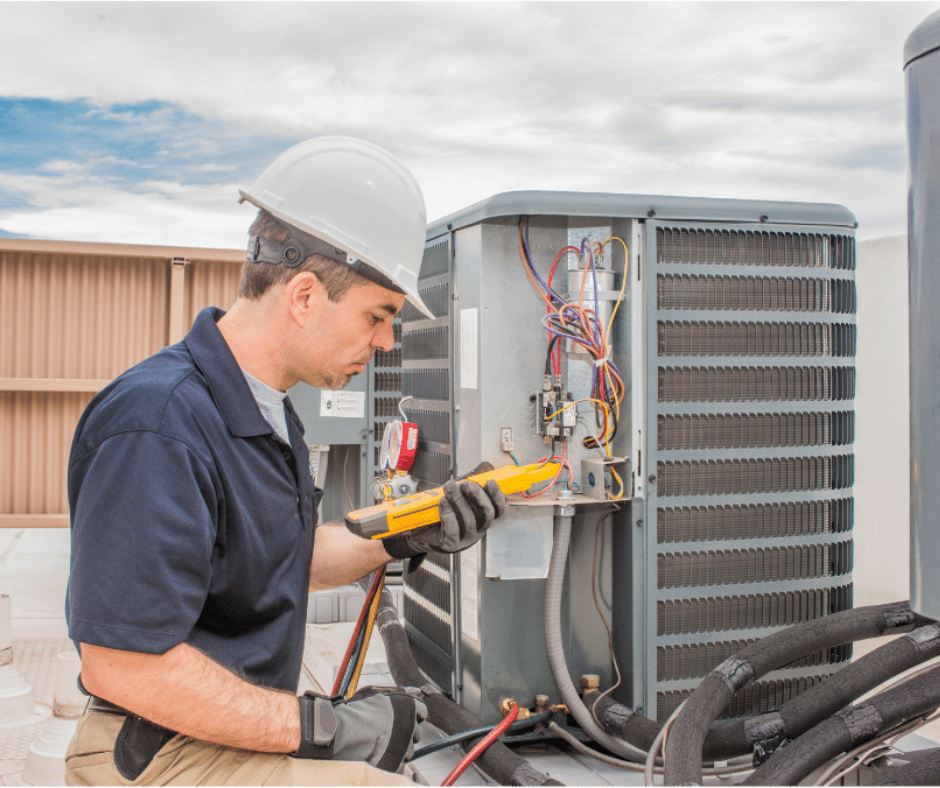
An HVAC program is like a car: you need to maintain it often to run efficiently. And just like cars, when preventative routine maintenance on an HVAC technique is neglected, smaller troubles can abruptly become expensive repairs. During a preventative routine maintenance visit, an HVAC technician will inspect the devices, check for any problems, and make confident all the aspects are clean up and free of charge from particles. They’re going to also test refrigerant ranges and make certain the unit is placing out sufficient air. And, of system, you can not forget about that pesky air filter. It can be significant to transform it consistently, much too – if not, you danger weak air excellent because of to dust buildup in your vents. On prime of that, if the air filter receives clogged with filth and debris, your HVAC system will gradually ramp up its power intake though driving up your electric power invoice at a breakneck velocity. So, make confident your air filters get replaced frequently – or else you’re inquiring for trouble!
One more aspect of the dwelling that must be checked consistently is the dryer vent. If the dryer vent gets clogged with dust and lint, it will outcome in a fewer-successful appliance and can lead to household fires – a catastrophe anybody would instead prevent. HVAC corporations typically supply duct cleansing products and services, so be certain to inquire when environment up preventative maintenance visits.
Electrical power Washing
How is power washing considered preventative servicing? Properly, possessing a rental property skillfully electric power washed at the time or twice a yr can make all the distinction. Absent are the times of fading paint and unsafe mildew – they can be easily replaced with a crisp, cleanse seem that will make any tenant come to feel far more at household. And it is not just about aesthetics eradicating slippery mildew from sidewalks is critical for making certain everyone’s protection. So if you have a rental property, make confident you give the exterior some notice with a great electrical power washing session.
Landscaping
Trying to keep up with the landscaping of your rental investment residence should be seen as a no-brainer: not only does it create a more nice ambiance for renters, but it also sets off a string of favourable domino outcomes that benefit the landlord even much more. Of class, it goes devoid of indicating that properly-manicured lawns, trimmed bushes and trees, and freshly mulched flower beds will draw in far more tenants – but they also enable preserve house value. A different thing to preserve in intellect is the irrigation method. If your home has a single, you must have it inspected at least the moment annually (the commencing of spring is a fantastic time) to make certain it’s ready for warmer temperature.
Landscaping can be much more than just an aesthetic difficulty. For example, if tree limbs are left untrimmed, they could quickly fall on the home’s roof, creating a mess you’d relatively not be dependable for remediating. More, clogged gutters can direct to h2o pooling all-around the home and quite possibly getting inside of. These are just a number of illustrations of how carefully preventative routine maintenance and security can be linked.
House Inspections
Typical home inspections are like a doctor’s stop by to your rental dwelling. The periodic verify-ups help ensure you’re hardly ever caught in a compromising predicament because of to deferred routine maintenance. By inspecting the premises, landlords can tackle any smaller routine maintenance issues in advance of they change into larger snafus. It also permits landlords to be certain their tenants retain the location upright, which could develop extra routine maintenance head aches. Over-all, inspections are an invaluable follow for individuals who possess rental home – they help landlords make guaranteed all the things is shipshape and make it possible for them to location any difficulty spots early.
Outcomes of Ignoring Preventative Upkeep
For tenants and landlords alike, the penalties of disregarding preventative routine maintenance can be disastrous. Right before you know it, an HVAC restore can turn into a complete-on alternative position, though a clogged dryer vent could spark off a residence fireplace – a person that could’ve been avoided by using care of some uncomplicated servicing. And for landlords in distinct, the cost tag for repairs only goes up the longer you disregard them – which is why it constantly pays to continue to be on top rated of them. So you should not get caught sleeping on the job – or your checkbook might wake up with a awful surprise.
Work with a Skilled Assets Administration Corporation
This maintenance may audio like a great deal and can be – which is wherever qualified house professionals appear in. A expert house administration corporation can mainly care for owners’ home maintenance. Experienced property administrators have near interactions with respected area distributors with verified documents of superb perform whom they can send out to your residence. Even more, they can enable you get on a regular preventative maintenance plan with HVAC companies, landscapers, and additional.
Don’t have time to examine your rental qualities? Really do not worry gurus can get care of that also. House managers know what to glance for throughout inspections and can recommend landlords on what objects need to have attention.
So, when preventative servicing is hugely essential, you don’t have to go it on your own: give your qualified property supervisor a call! 
As a primary house administration agency in the Cape Concern location, Sweyer Property Management suggests that house entrepreneurs strongly take into account performing with a reliable and expert assets administration company. Regardless of whether it pertains to the eviction course of action or a further region of managing your financial investment properties, we want to make absolutely sure property entrepreneurs and traders have an understanding of the marriage they are coming into into when picking to work with a home management business.
If you have investment houses and do not use a qualified management business, we hope you think about performing so. The authorities at Sweyer House Administration will be satisfied to provide you with a free of charge rental evaluation or, if you like, give us a contact at 910-239-1338. 

 Sweyer Home Management is a complete-provider qualified residence management firm specializing in all elements of rental administration. If you might be an investor or residence proprietor hunting to learn additional about our providers and what a expert property manager can do for you, get to out to us nowadays at 910.256.3031 or by means of our web-site. Sweyer Residence Management has exhibited ongoing progress during the Wilmington, Leland, and Hampstead regions though retaining an excellent Google+ rating for shopper company.