Geographic Risks of Rental Property Ownership

Geographic Risks of Rental Property Ownership

Picking the right area to invest in real estate is hard enough. But add numerous unprecedented developments to the mix—a pandemic, high interest rates, and Americans fleeing to secondary cities at historical rates—and the risk of leveraging wealth to a mortgage in the wrong location feels especially greater than buying a share of a REIT investment.

Here, we take a closer look at geographic risk’s impact on direct real estate investments.

Why REITs Have Lower Risk Than Direct Real Estate

REIT management teams often invest in hundreds of properties across various sectors and markets, ensuring that investors take on lower geographical risks and higher diversification.

Additionally, REITs tend to come with fewer risks than rental properties because they:

  • Develop their own properties.
  • Are managed by real estate experts.
  • Offer fewer options to choose from than investment properties.
  • Can expand externally by raising capital through the public equity market.
  • Historically provide a tight range of returns.

The chart below highlights the consistency and predictability of the annualized return from investing in a REIT index for a decade, starting anytime between 1991 and 2012.
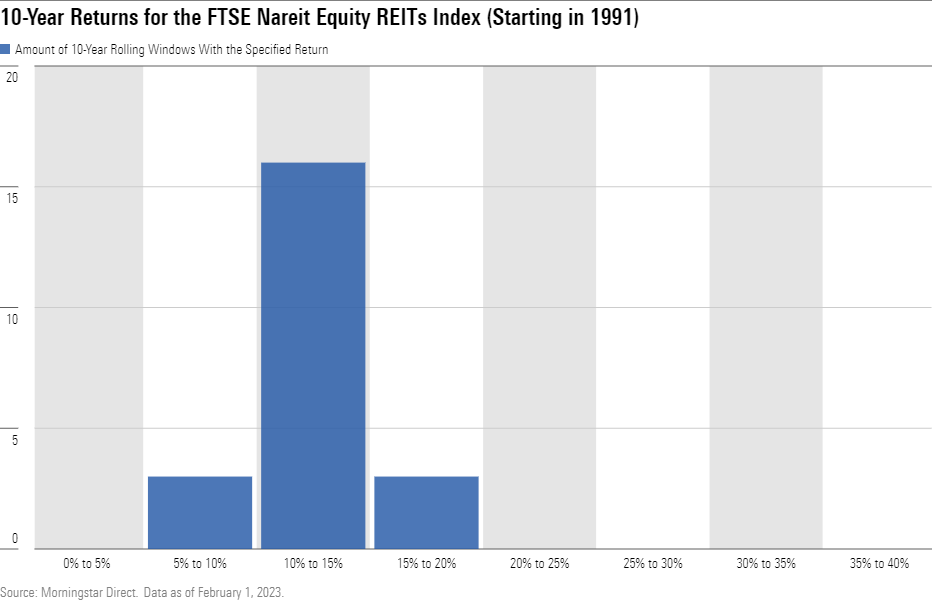
A bar chart highlighting the consistency and predictability of the annualized return from investing in a REIT index for a decade, starting anytime between 1991 and 2012.

What Are the Risks of Investing in Real Estate Directly vs. REITs?

Buying and owning property is rarely easy, especially because it’s hard to predict if a neighborhood will start to trend downward, lowering the resale value and rental prices to attract long-term tenants.

For example, consider direct real estate investors who owned a rental property (leveraged at 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} equity) for at least 10 years, starting anytime between 1991 and 2012 in any of the 100 biggest metropolitan statistical areas, or MSAs. They would have experienced inconsistent and sporadic compound annual growth rates based on the investment time window and property location, as shown in the chart below.
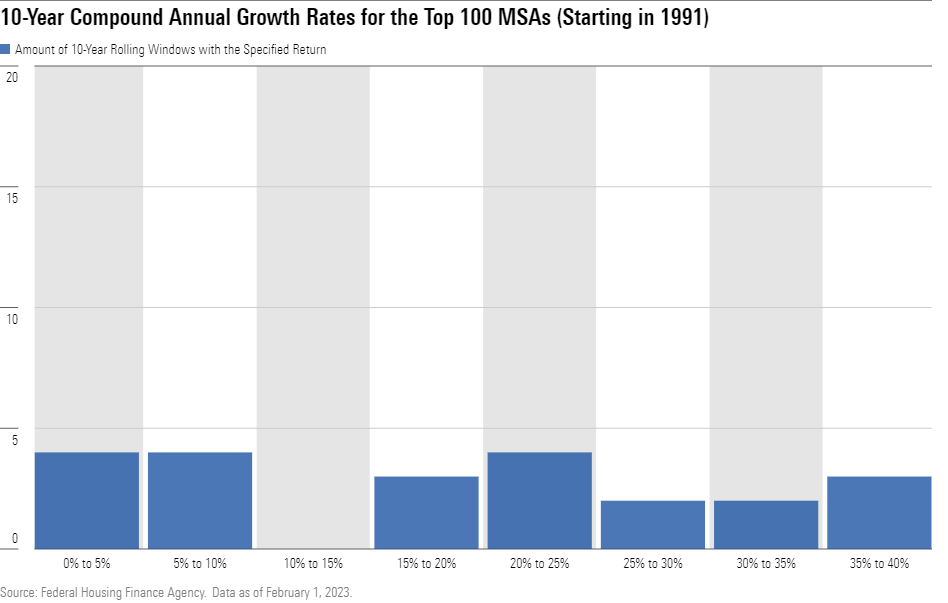
A bar chart showing that investing in physical real estate can have significant geographical risks.

This inconsistency happens because investing in physical real estate can have significant geographical risks. For example, our analyses indicate that while property price returns often ranged between 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and 25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} across the Central, East, and West regions in the United States in the past 32 years, it was more likely to fall below that range when investing in the Central and East regions.

On the other hand, you were more likely to reach peak returns in the West, as early investors in West Coast cities saw their properties appreciate faster than homes in any other region. That said, you had to get into that market at the right time: Investors today are likely to pay a hefty price to enter the market and need to make a sizable down payment to see immediate positive cash flow on a rental property.

Meanwhile, despite more modest returns, the housing markets in the Central and East tend to be more affordable, allowing home prices to cool down slowly after a housing boom.
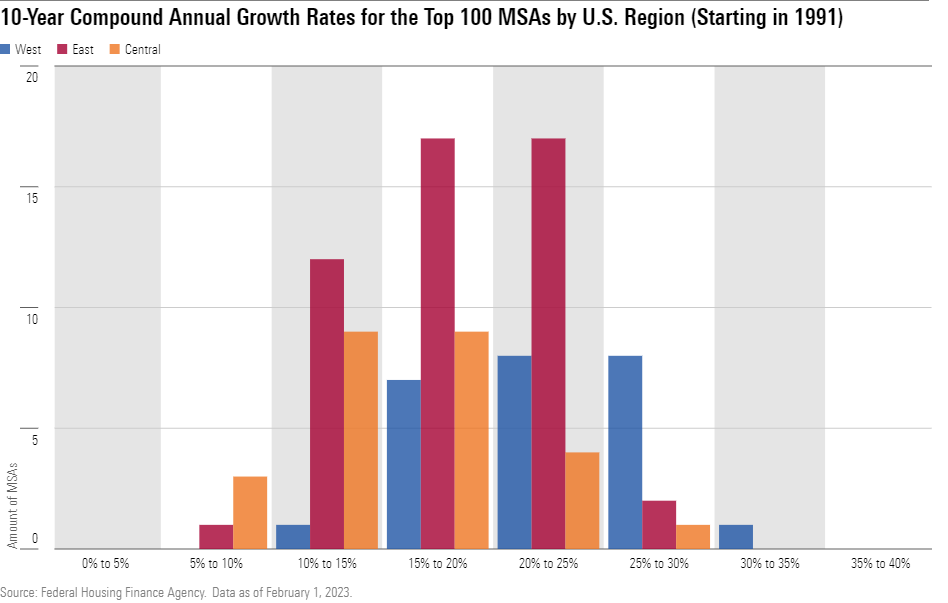
A bar chart showing property price returns over the past 32 years across the East, West and Central regions in the United States.

Even within the same market, the range of potential return outcomes can be broad and complex to navigate.

For example, take Tampa Bay and Houston—two comparable Sun Belt cities. Your real estate returns in these two cities would have varied substantially depending on the decade when you bought your property. If you made your investment 1) in the 1990s, you would have seen greater long-term returns in Tampa Bay; 2)between 2000 and 2008, you would have withstood the effects of the housing crisis better in Houston; or 3) after 2009, you would have seen positive growth for both cities, especially in Tampa Bay.

The highs and lows of Tampa Bay and the long run of mediocre returns from Houston may make it surprising that they currently are among the most thriving areas in the real estate game.

Early investors who capitalized on the low costs of real estate development in the South now enjoy the fastest-growing home sales prices. While it may make sense that cities with warm weather, affordable housing, and low tax rates are good areas to invest in, it’s harder to know when you should invest and how long you should hold.
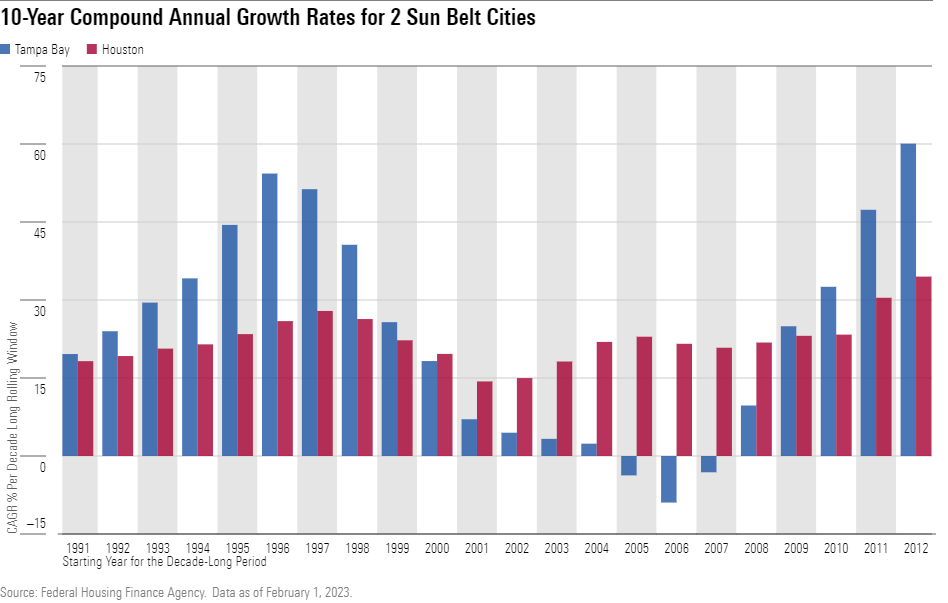
A bar chart showing that real estate returns in Houston and Tampa Bay would have varied substantially depending on the decade when you bought your property.

The Complexities of Predicting Real Estate Winners

In hindsight, the benefits of investing in the Sun Belt cities after the housing crisis seem obvious. However, property markets quickly rise and fall, so picking the right time and location for an investment is easier said than done.

If you’re newer to real estate, reviewing historical trends can be a helpful guide. So, let’s turn back the clock about 20 years, to 2001. Despite being in the midst of an economic recession, there was unexpectedly high performance in the housing sector.

  • There were new annual records for home sales and homeownership.
  • Mortgage rates were at near all-time lows.
  • Housing affordability was the most favorable in the past 28 years.

Real estate professionals around the country anticipated that the increase in home supply would make early 2002 a good time to buy, even if interest rates were slowly beginning to rise—defying an economy in recession.

Let’s say you had the ability to purchase a property in a large metro area at the beginning of 2002 for $500,000 and hold it for 20 years. Which area would you pick? Below you’ll find more information to help guide your decision.
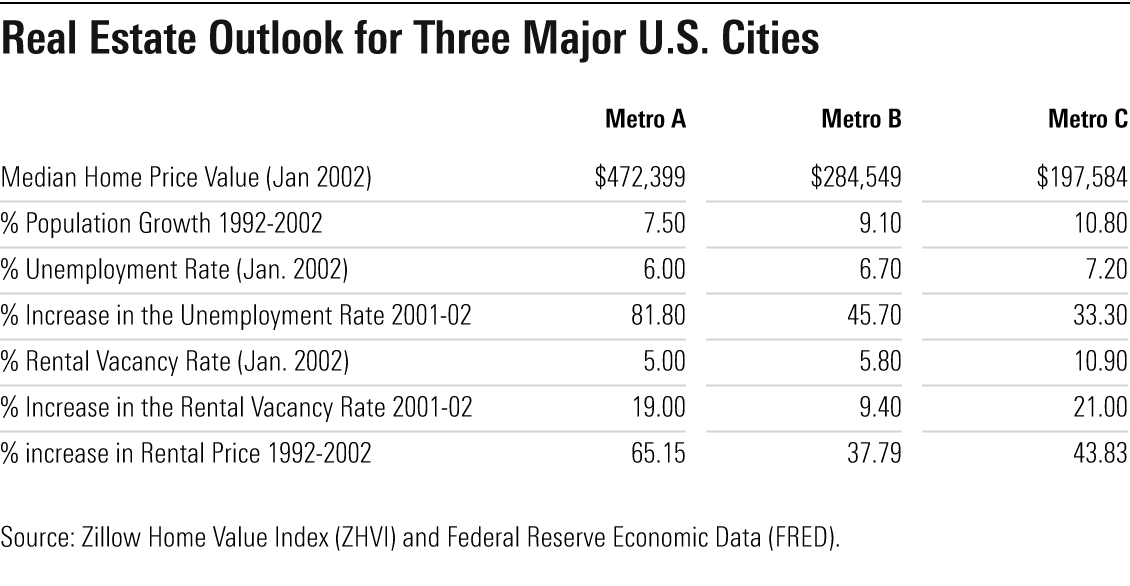
The chart provides information about each MSA to help guide your decision.

  • Metro A faced a downward spiraling disaster after the dot-com bubble left many people unemployed and forced them to leave the area, causing vacancy rates to climb. While the market was considered a real estate gold mine in the late 1990s, its heavy dependence on the troubled technology sector led economists to anticipate a slow economic recovery and an uncertain future.
  • Metro B faced a more mixed picture. In 2001 alone, more than 25 companies relocated out of the area, increasing unemployment rates and reducing the number of building permits. On the other hand, sales of existing single-family homes and sales prices were up from the previous year despite an economic slowdown.
  • Metro C had another excellent year in residential construction and home sales as property prices remained relatively low compared with the national average. In addition, despite relatively high unemployment rates, there were plans for an automotive-supplier project that would introduce hundreds of manufacturing jobs to the area.

Still undecided on which metro area would have been the best long-term investment? You’re not alone.

Real estate investing was much murkier in the early 2000s, as the current top housing markets weren’t necessarily the prime locations from 2002 to 2012. In fact, since 2002, more than 300 of the top 500 metro areas appreciated less than the U.S. average, including 28 of the largest 50.

Here’s how each of those investments would have fared:

  • An investment in Metro C (Chicago) would have seen your capital appreciation grow at a lower rate than the national average. Yes, your property value would have increased to $800,000 by 2022, but that falls $400,000 short of the U.S. average due to a relatively low annual home growth rate after 2006. Since then, income and property taxes have gradually risen, and the lack of employment opportunities has caused residents to leave the city at unprecedented rates.
  • An investment property in Metro B (New York) would have performed around the national average, with your home value rising to $1.1 million by 2022. New York City’s recovery after the 2008 housing crisis was particularly strong as people continued to flock to the area and residents were more likely than average to keep their jobs and avoid foreclosure. However, strengthened rent controls and low capitalization rates have made New York a complex property investment choice unless you are focusing on the luxury marketplace, which is still one of the most expensive housing markets in the world.
  • Metro A (San Francisco) would have seen the best returns of these three options. Your investment property would have experienced an eye-popping 300{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} growth in its value, turning that $500,000 investment property into $1.5 million. In 2002, it would have been hard to believe that one of the best future housing markets would be led by the development of internet-related companies, considering that the industry had just lost more than 75{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of its market value during the dot-com bust.

But then again, these strong returns highly depend on when you invested.

As many big technology companies weathered the storm in California, Silicon Valley became home to the hottest residential bidding wars, reaching a peak in 2012.

Strict zoning laws combined with the limited amount of land have made real estate scarce in San Francisco compared with other California areas. However, high property prices, strict rent-control regulations, and tenancy rights make it extremely difficult to be a successful new real estate investor in San Francisco unless you are willing to provide a significant down payment for immediate positive cash flow.
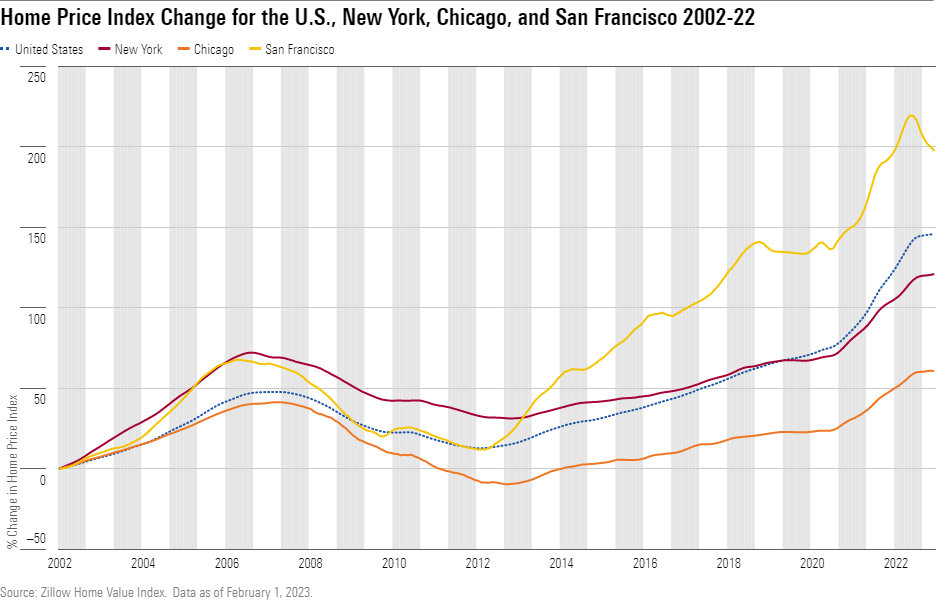
A line chart of changes in the Zillow Home Value Index from 2000 through 2022 in the U.S., Chicago, San Francisco, and New York.

Picking Real Estate Winners Is Only Simple in Hindsight

While home appreciation can be compelling for rental properties, finding the location that will grow a property’s value the fastest with the greatest return can be highly speculative. The stakes are especially high for homeowners who borrow up to 80{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the home price value. On the other hand, REIT management teams strategically finance their investment properties with 30{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 40{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} leverage, allowing for higher liquidity during economic distress.

Even those who invest a significant amount of their wealth in a property are exposed to unprecedented outside risks. Each market is unique, regardless of the location you decide to invest in, and some secular dynamics are harder to identify than others. For example, the Chicagoland counties accounted for some of the largest numbers of homeowners with underwater mortgages, as lackluster job and pay growth pushed residents to move out of the area.

Unless you have a time machine, factors like these may be beyond your ability to forecast. That said, for those who get the timing right, the rewards can be great when investing directly in real estate.

Buying an investment property in Canada: Risks, taxes, regulations and lower-cost alternatives

Buying an investment property in Canada: Risks, taxes, regulations and lower-cost alternatives

Serious estate is its individual asset course, featuring various characteristics from equities and fastened profits. As these kinds of, it can enable diversify prosperity. Investing in real estate does not call for specialised knowledge most Canadians have an understanding of the principles of holding property by means of dwelling possession. Numerous have accomplished pretty well due to residence selling price appreciation about the earlier two a long time.

The inflation-altered returns for real estate over the previous 50 several years in Canada are pretty equivalent to that of equities. But individuals returns came with much a lot less volatility than stock marketplaces. In addition, income varieties a even bigger part of its total return when compared to stocks, which are additional about money gains. So genuine estate may possibly be a extra acceptable financial commitment for cash flow-oriented buyers this sort of as retirees. But younger investors, also, can consider benefit of the leverage uniquely out there to serious-estate buyers banking institutions will readily lend you up to 4 situations your money at favourable prices to get true estate, wherever they won’t do that if you are buying stocks or bonds.

“As the property appreciates, the return on first expense for your down payment can be much increased thanks to the leveraged total,” reported Sabine Ghali, managing director of Buttonwood Assets Administration in Toronto. Of study course, as many landlords are finding this calendar year, leverage performs the other way, way too when assets values arrive down, the mortgage principal owed continues to be just as complicated.

What are the threats of investing in authentic estate?

As opposed to other assets, authentic estate is illiquid. It takes time to locate a suited house to acquire or a ready buyer for a assets you’re promoting. When you do, the expenditures of the transaction are significant, normally upward of 5 for every cent of the price tag for the seller. That features agent commissions, legal expenses, inspections and other 3rd-bash bills, but not your personal time.

Simply because investment decision attributes begin at about $100,000 in Canada, and most cost several instances that, it’s a tough sector to wade into incrementally. Even with mortgage loan financing, you have to have at the very least a middling internet really worth to participate. (See a list of decreased-cost different approaches of getting authentic estate publicity underneath.)

While much less volatile than the stock marketplace, assets markets fluctuate. Ought to fascination costs increase though you personal the property, its benefit could minimize even as you facial area higher mortgage loan payments on renewal. Economic and work prospective buyers in the community subject, too, as does excellent of daily life. There are individual challenges to your house of hearth, destruction and all-natural disasters. You can get insurance policy for that.

What’s more challenging to handle is the romantic relationship with your tenants. An exacting process to screen prospective tenants, including a credit score check out and interviewing employers and past landlords, can go a long way toward reducing potential complications, in accordance to Ms. Ghali. Provincial laws lays out a process for dealing with disputes in between tenants and landlords, nevertheless rental tenancy laws and tribunals tend to err on the aspect of the previous. Ally Ballam, a genuine-estate adviser with Engel & Volkers in Vancouver, suggests entrepreneurs maintain a few to six months’ lease in a individual account just in scenario there’s a dispute and you go a couple of months devoid of receiving profits from the home.

Last but not least, there is a hazard of emptiness, whether or not resulting from tenant churn or adverse industry conditions. This chance can hardly ever be removed entirely but can be minimized by possessing higher-top quality properties in favourable areas.

“Buying a home for investment decision functions that can be your main home if the marketplace turns seriously terrible is generally a awesome insurance policies plan,” Ms. Ghali stated.


What taxes and laws apply to financial investment assets?

Compared with a principal home in Canada, investment decision home is issue to funds gains tax when you offer it. You ought to also pay out profits tax on the rental cash flow even though you individual the property. Each will consume into your returns. Having said that, these taxable amounts can be partially offset by costs incurred from financing, protecting, handling and strengthening the residence. It is worth consulting a tax adviser to decrease your taxes payable, at the very least when it comes time to sell.

The pros and disadvantages – and tax implications – of proudly owning cash flow home

Also make oneself conscious of provincial, municipal and apartment corporation regulations relevant to any house you’re taking into consideration buying. Some provinces and municipalities have controls on hire, which may constrain your potential to increase it to the market rate. British Columbia and Ontario have both equally launched taxes on properties ordered by overseas consumers (not Canadian citizens or permanent residents). Vancouver and Toronto both have levied property surtaxes on houses considered to be vacant, and other towns are contemplating adopting related measures as a way to increase the housing provide.

Many Canadian municipalities restrict or totally ban shorter-time period rentals in specified housing kinds. Additional, apartment organizations may undertake limits, for case in point on brief-time period rentals or the proportion of models in a creating that can be rented out.


Is now a great time to commit in actual estate?

The good information for future customers: Right after big selling price appreciation in modern many years, most Canadian marketplaces are going through a flip and selling prices are coming down.

The bad information: The major element pushing prices down is the maximize in borrowing prices. So for most customers, the drop in selling prices will be offset by greater house loan payments.

Is your mortgage leaving you dwelling poor? Use our True Lifestyle Ratio calculator

The takeaway: This is a potentially perilous time for buyers with only a 20-for each-cent down payment (the minimum expected by creditors on investment decision houses) to get into the market. If you are in that predicament, you’d far better be confident you are paying underneath industry price. It may possibly be an opportune time, even so, for men and women who possess their residence outright, have some further income and really do not have to have to borrow enormous sums to get into the expenditure property marketplace. If financing is not a massive be concerned, your dollar will go even more these days than it has in a although.

Preserve in mind that serious-estate marketplaces are notoriously area. Different dynamics will be at play in Sudbury and suburban Montreal. Time and once again, income trends immediately after the actuality propose there’s virtually constantly a variety of house somewhere in Canada that is a steal suitable now. The challenge is obtaining it (or them).


How do I invest in authentic estate?

You research for an financial investment property to buy the same way you may possibly do your have house: search at listings, interact a true estate agent and/or research on commission-free revenue platforms. The most extensive general public database of Canadian households for sale can be identified at realtor.ca.

But there are other avenues to uncover the greatest deal. Ms. Ballam and income associate Amy Leong focus in working with builders to give their purchasers pre-sale condos at charges commonly reserved for insiders in advance of they are offered to the normal public.

“Make absolutely sure when you are looking to buy an financial investment house that you are working with an agent who specializes in financial investment qualities,” Ms. Ballam advises. They will, for instance, run pro forma income movement projections for your rental money and bills below distinctive property finance loan-price scenarios so you have a far better plan of what you’re finding into.

In addition to an agent, you will probable require other company suppliers, this sort of as a lawyer, assets inspector and home finance loan broker, to get the transaction finalized.


What do I need to have to do immediately after I get an expense residence?

If you have the time and inclination, you can reduce your expenditures and likely improve your returns by taking care of the residence oneself. That entails locating and dealing with tenants, amassing lease, observing to upkeep and repairs (together with soon after-hrs emergencies), and shelling out residence taxes as well as relevant utility and other charges. You will have to have property insurance plan it will be to some degree higher than for an operator-occupied space. Conventional lease files can be downloaded from most provincial internet sites that will assist lower the chance of authorized disputes, which can probably drag out for months, interrupt your rental profits and incur main expenditures.

Alternatively, you can employ the service of a house-administration company, which will do most or all of the jobs listed earlier mentioned for 8 to 10 for every cent of rental profits on prolonged-time period rentals and 12 to 15 for every cent on quick-term kinds. Your serious-estate agent can refer you to these kinds of a agency in your region, but like something else, it’s worth buying close to. Some serious-estate revenue and finance providers have their own property-administration products and services arms.

Like any important investment, you really should have a system. Do you intend to flip the assets in a rapidly-rising market place? Maintain it lengthy-expression? Renovate it in the hope of raising the rent? For traders committed to the asset class, Ms. Ghali recommends banking rental money with the aim of acquiring a further house each individual 3 to 5 yrs: “This electrical power of compounding extra on top of the leverage aspect of authentic estate investing can make probably substantial gains above a extended interval of time.”


There are a amount of means for traders of modest usually means to attain publicity to genuine estate without getting a second dwelling or the headache of managing the house.jhorrocks/iStockPhoto / Getty Photos

Are there decreased-charge techniques to get publicity to serious estate?

The millennial lament about shopping for a house, epitomized by the hashtag #donthaveamillion, is also a major hurdle for would-be investors. The good thing is there are a selection of techniques for buyers of modest suggests to get exposure to true estate with no acquiring a 2nd home or the trouble of handling the home.

REITs

Real-estate investment trusts are securities that trade on stock marketplaces. They are designed to maintain and take care of a basket of qualities and pass on cash flow through distributions (related to company dividends) to investors. With REIT units or an exchange-traded fund (ETF) invested in them, you can profit from both of those land worth and lease will increase in the genuine-estate marketplace for as little as $100. Becoming traded on stock marketplaces, they nonetheless are inclined to be remarkably correlated to equities.

Fintech

For the previous decade or so, economical know-how startups have been trying to arrive up with means for tiny buyers to get crowdfunded attributes fractionally for as little as a number of thousand bucks for each investor. Canadian illustrations include Addy Engineering Corp., BuyProperly, NexusCrowd and Willow Serious Estate Technologies. On the moreover side, these platforms promise to be genuine diversifiers, in which your investment’s value is tied to serious property. Even now, they have a small observe report and are competing with very well capitalized landholding firms owned by pension funds, REITs, personal-pooled money and wealthy households and men and women.

Serious-estate pooled money

For a minimum financial commitment as high as $100,000 and a lock-in period, non-public genuine-estate investment resources permit investors to participate in possessing (and sometimes establishing) rental homes all over North America. Adhere to typical companions with a heritage and great track record there are some shady operators in this niche. Beware promotions promising suspiciously substantial or “guaranteed” returns and usually demand to see fiscal statements prior to putting your dollars down.

Investing in your possess household

Owners in Canada’s expensive, major-metropolis marketplaces presently know about “mortgage helpers” these kinds of as basement suites. Adding or improving a rental suite in your own home or constructing a laneway residence represents a way to leverage your present principal home to deliver additional income and increase the fairness in your residence. It is basically an investment decision property tacked onto your residence.

As these kinds of, be conscious of charges that can erode your fee of return. Even though little, new laneway properties even now require the most high-priced elements of any residence, particularly kitchens, loos and HVAC units. But it need to nonetheless be much less expensive than purchasing a separate residence.

No space for a independent suite? Now that COVID-similar journey constraints have been lifted, international college students are coming again to Canada. You can produce revenue by renting out a spare space. There are numerous organizations that match pupils to host homes below a assortment of phrases.

How to Mitigate Risks When Purchasing an Investment Property | Featured

How to Mitigate Risks When Purchasing an Investment Property | Featured

Despite the fact that an expenditure house can create a healthier revenue, this does not necessarily mean this sort of ventures come without threats. In truth, investing in a assets which is in terrible issue and/or situated in an location with minimal housing need could verify financially ruinous. That staying the circumstance, it is in each and every investor’s most effective curiosity to mitigate threats when getting an investment decision residence. Anyone looking to reduce their odds of winding up with a lemon of an financial commitment house can profit from the next ideas.

How to Mitigate Risks When Purchasing an Investment Property | Featured  

Study Local Housing Demand 

No matter how nice a house is or how effectively it’s been managed, it is not likely to change a handsome revenue in an area with small demand for housing. So, if you have at any time puzzled why so many realtors are eager on the mantra “Location, site, area,” that is one mystery solved. To a lot of realtors – and additional importantly, many house-seekers – the spot of a home will take priority more than the assets itself. For case in point, a tiny, amenity-light-weight assets in an space with significant desire is possible to produce a larger sized gain than a significant, amenity-abundant house in an spot with small desire.  

So, ahead of acquiring begun on any paperwork, make certain to investigation local housing desire. Much more normally than not, big metropolitan places with robust career markets and ample leisure pursuits have a bigger degree of desire than more compact locations with very poor neighborhood economies. Of class, this isn’t to say that every single high-desire place is in the vicinity of a massive metropolis – or that every single low-need location is a modest neighborhood. 

Perform with a Seasoned Investment decision Company 

If this is your to start with time investing in any variety of authentic estate, you could advantage from the assistance of well-informed authorities. So, if you have any buddies, spouse and children members or other acquaintances who have expertise with financial investment qualities, you have practically nothing to get rid of by looking for out their information. You also stand to advantage from operating with a very-rated financial investment corporation. A company like OmniLytics can deliver you with the info you have to have to successfully lessen pitfalls and maximize income.    

Have the Home Inspected 

You should in no way invest in a home that has not been completely inspected. No matter how nice a home seems from the outdoors or how thorough a walkthrough you’ve personally done, it is imperative that you function with a licensed dwelling inspector. These men and women are trained to detect a broad assortment of troubles that are probably to escape the gaze of nonprofessionals, and the complete final issue you want is to get stuck with a assets that demands comprehensive repairs and/or renovations you had no idea were important. 

If a vendor firmly pushes again against the prospect of a experienced inspection, tell them that an inspection is a prerequisite for your involvement. As a consumer, you only stand to advantage from an inspection getting spot. For a single detail, the benefits of the inspection will make sure that you know specifically what you are finding, so serving to you make an educated choice. Next, if the inspector uncovers any earlier-unrevealed concerns with the house, your bargaining placement will be considerably much better.   

Look at Repairs Costs 

If you’re intrigued in investing in a rental assets, it is essential that you thoroughly think about the upkeep costs. For illustration, if you are searching to buy a modest one-family members assets, administration and maintenance expenses are likely to be relatively acceptable. Nevertheless, if you have your sights set on a massive multi-relatives residence, the aforementioned expenses are liable to consume up a huge part of your month-to-month gains. Apartment and apartment complexes with dozens of units normally involve onsite administration and comprehensive-time upkeep personnel, so when calculating monthly expenses, consider care to factor in the salaries of any upkeep specialists or residence professionals with whom you intend to perform.  

Financial investment homes can rake in a substantial amount of money of money each individual thirty day period. However, believing that each individual expenditure home you appear across will verify equally rewarding is pure folly. Offered how big a economic sacrifice the typical rental home represents, it’s in every single investor’s finest curiosity to mitigate pitfalls when seeking out the excellent properties. To assist be certain that you really do not occur down with an acute circumstance of buyer’s regret, place the guidance outlined above to good use in your search for the appropriate financial investment home.  

10 Investment Property Risks and How to Minimise Them

10 Investment Property Risks and How to Minimise Them

Cheapest desire premiums for 1-yr mounted household loans

The comparison desk under displays some of the 1 calendar year set amount expense residence bank loan solutions on Canstar’s database with back links to lenders’ web sites out there for a personal loan amount of money of $350,000 at 80{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} LVR in NSW, and offered for Principal and Fascination repayments. The outcomes are sorted by comparison charge (least expensive to best), then by provider name (alphabetically). Right before committing to a certain home personal loan products, test upfront with your loan provider and read through the applicable financial loan documentation to verify whether the conditions of the financial loan satisfy your needs and compensation capability. Use Canstar’s household financial loans comparison selector to view a wider assortment of house mortgage goods. Canstar might receive a rate for referrals.

*Comparison fee based on financial loan amount of $150,000. Study the Comparison Charge Warning.

Most affordable fascination rates for 3-year preset home loans

The comparison desk under displays some of the 3 calendar year fixed rate expenditure household loan items on Canstar’s database with hyperlinks to lenders’ sites readily available for a bank loan total of $350,000 at 80{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} LVR in NSW, and available for Principal and Desire repayments. The effects are sorted by comparison fee (least expensive to optimum), then by provider name (alphabetically).Ahead of committing to a unique property loan products, test upfront with your lender and study the relevant loan documentation to verify regardless of whether the phrases of the personal loan meet up with your demands and reimbursement capacity. Use Canstar’s house financial loans comparison selector to perspective a wider range of residence mortgage solutions. Canstar may well earn a cost for referrals.

*Comparison price dependent on personal loan amount of $150,000. Read through the Comparison Rate Warning.

Lowest fascination costs for 5-12 months fixed residence loans

The comparison tables down below shows some of the 5 calendar year preset rate expenditure home financial loan goods on Canstar’s databases with one-way links to lenders’ internet websites accessible for a bank loan sum of $350,000 at 80{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} LVR in NSW, and out there for Principal and Fascination repayments. The results are sorted by comparison level (most affordable to optimum), then by service provider title (alphabetically).Just before committing to a specific household bank loan solution, look at upfront with your financial institution and study the relevant personal loan documentation to validate regardless of whether the phrases of the personal loan meet up with your requires and reimbursement capability. Use Canstar’s house financial loans comparison selector to watch a broader selection of residence bank loan goods. Canstar may earn a charge for referrals.

*Comparison price dependent on mortgage sum of $150,000. Go through the Comparison Level Warning.


7. Funds circulation

Hard cash stream is the net revenue that the house trader earns after paying out off an financial commitment property’s bills, taxes and home loan repayments. Damaging funds circulation is experienced when the costs exceed the rent collected. In this sort of conditions, you have to have to use other income resources to pay back for the property. As a result, cash movement risk has the likelihood of producing a negative money move of a far more major magnitude than envisioned.

How to minimise this hazard

  • Forecast your earnings and costs and make it possible for for contingencies.
  • Create a sizeable home portfolio with enough hard cash stream to aid your requirements.
  • Talk to a residence strategist to support you plot your extended-term tactic and create your home portfolio in accordance to your circumstances and danger hunger.

8. Deficiency of liquidity

A major risk precise to true estate investing is that houses are illiquid, that is, they cannot be effortlessly converted into income. This hazard manifests when an trader is forced to provide a home at an unwanted selling price due to their money or individual situation.

How to minimise this threat

There is no quick remedy for handling this possibility, so you really should embrace it by preserving liquidity in your portfolio. Having said that, it would be better to stay away from it altogether by creating a buffer of liquid investments or income. When contemplating your acquisition, consider your will need for liquidity and commit wisely.

9. Own risk

Financial investment portfolios could be negatively impacted by various unforeseen elements, together with reduction of money thanks to personal injury, divorce or job loss. These are termed own dangers.

How to minimise this danger

To mitigate this threat, you should really consistently overview your lengthy-phrase technique and invest in building a positive cash circulation residence portfolio. In other phrases, you should really have a neutral-to-optimistic geared portfolio, making certain that your expenditure portfolio does not rely on your contributions. Nevertheless the particular person properties can chase growth or hard cash move, be certain that your in general investment portfolio does not have to have as well substantially of your cash to work.

A further successful way to mitigate the chance is to insure your self. All home traders should have life insurance policy and revenue security. 1 of the obligations of buyers is their potential to assistance their loans whilst growing their residence portfolio. In the same way, for unexpected instances this kind of as death or harm, you have to have to make certain your spouse and children will be able to maintain the financial commitment properties.

Consequently, it is significant to consult with a experienced insurance policy broker and an accountant to get tips on the style and level of covers essential.

10. Foreclosures danger

This danger manifests when an investor just cannot pay their mortgage payments on time for a extended period they default on their financial loan obligations so the loan provider forecloses.

How to minimise this risk

You can regulate the foreclosures threat by making sure all your repayments are designed on time. You need to also have an unexpected emergency fund to address a handful of months’ worthy of of repayments. Eventually, parking money in an offset account will decrease the interest you are billed and give you with liquidity and versatility at the exact time.

The Property Wealth Blueprint


This is an edited extract from The Home Wealth Blueprint by Rasti Vaibhav ($39.95) republished with permission.


Cover impression supply: Soho A Studio/Shutterstock.com


Rasti VaibhavAbout Rasti Vaibhav

Rasti Vaibhav (B.Arch, M.Comp, MBA, CFA) is the founder of prospective buyers company firm Get Uncommon Qualities. He is a licensed impartial buyer’s agent, house professional and long-term home trader, who specialises in assisting dwelling purchasers and buyers obtain the correct home at the appropriate price tag Australia-wide.


Thanks for going to Canstar, Australia’s major monetary comparison site*