2022 marked the end of cheap mortgages and now the housing market has turned icy cold : NPR

2022 marked the end of cheap mortgages and now the housing market has turned icy cold : NPR

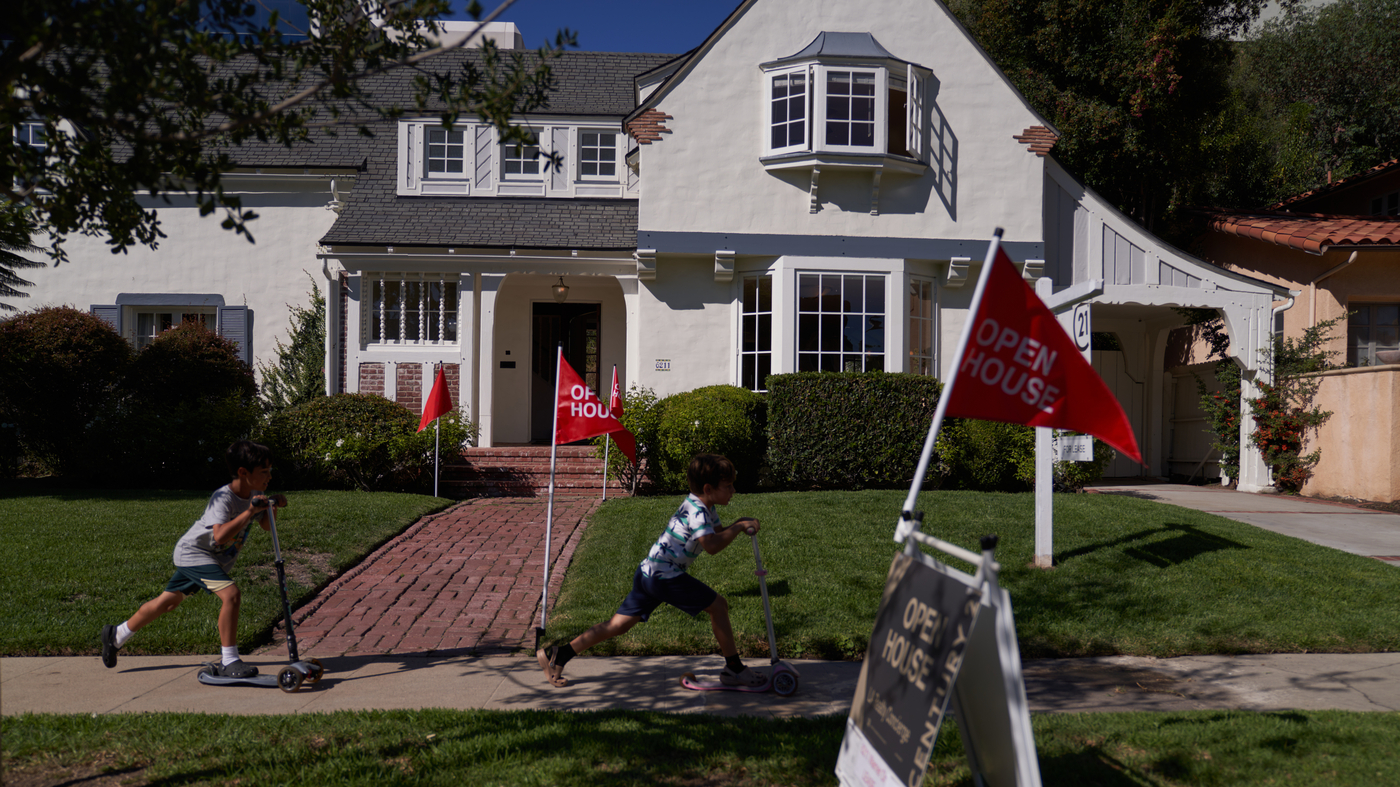
Small children journey scooters earlier a household for sale in Los Angeles. Home profits have slowed as house loan costs have climbed.

Allison Meal/Getty Visuals


cover caption

toggle caption

Allison Meal/Getty Photos

Youngsters trip scooters previous a house for sale in Los Angeles. Home revenue have slowed as home loan prices have climbed.

Allison Evening meal/Getty Visuals

Evan Paul and his spouse entered 2022 contemplating it would be the 12 months they would at last get a household.

The couple — both of those scientists in the biotech field — have been ready to place roots down in Boston.

“We just sort of got to that position in our lives where we had been financially quite stable, we desired to start out getting young children and we desired to just type of settle down,” states Paul, 34.

This year did deliver them a infant woman, but that home they dreamed of by no means materialized.

Superior household selling prices were the preliminary insurmountable hurdle. When the Pauls initial begun their research, small curiosity premiums at the time had unleashed a purchasing frenzy in Boston, and they were relentlessly outbid.

“There’d be, you know, two dozen other offers and they’d all be $100,000 about inquiring,” claims Paul. “Any any time we tried to wait around until finally the weekend for an open property, it was long gone in advance of we could even appear at it.”

Then came the Fed’s persistent desire costs hikes. Right after a few months, with home loan rates climbing, the Pauls could no longer afford the households they’d been wanting at.

“At to start with, we begun decreasing our anticipations, wanting for even scaled-down houses and even fewer ideal spots,” says Paul, who eventually realized that the superior house loan rates have been pricing his spouse and children out all over again.

“The anxiousness just caught up to me and we just made the decision to simply call it quits and keep off.”

Purchasers and sellers set strategies on ice

The sharp enhance in home loan charges has forged a chill on the housing current market. Lots of customers have paused their lookup they can longer find the money for home selling prices they had been taking into consideration a year back. Sellers are also cautious of listing their houses since of the large property finance loan charges that would loom about their following order.

“Men and women are caught,” claims Lawrence Yun, main economist with the Countrywide Association of Realtors.

Yun and many others explain the sector as frozen, just one in which house gross sales action has declined for 10 months straight, according to NAR. It is really the longest streak of declines because the team begun tracking sales in the late 1990s.

“The sellers aren’t placing their residences on the current market and the purchasers that are out there, absolutely the electrical power of their greenback has changed with growing desire fees, so there is a minimal little bit of a standoff,” claims Susan Horowitz, a New Jersey-centered genuine estate agent.

Curiously, the standoff has not had considerably impression on rates.

Dwelling prices have remained mostly superior regardless of the slump in income exercise mainly because stock has remained low. The inventory of unsold present homes fell for a fourth consecutive thirty day period in November to 1.14 million.

“Just about anything that will come on the industry is the a person salmon functioning up stream and every bear has just woken up from hibernation,” claims Horowitz.

But even that development is beginning to crack in some markets.

At an open home for a charming starter property in Hollywood a single modern weekend, agent Elijah Shin failed to see several folks swing as a result of like he did a yr back.

“A 12 months back, this probably would’ve already marketed,” he says. “This home will provide, way too. It can be just going to choose a small little bit more time.”

Or a lot lengthier.

The cottage 1st went on the market back again in August. 4 months afterwards, it’s nonetheless waiting for an present.
Why Getting A Specialist Mortgage Broker Can Be A Boon For You!

Why Getting A Specialist Mortgage Broker Can Be A Boon For You!

Buying your own house is a huge step forward in everyone’s life. It might even be the biggest purchase of your life. Often, this dream can feel far-fetched if your financial circumstances are complicated, putting you in a position to borrow more money and receive extravagant interest rates.

You can minimise all your hassles in getting the best out of your mortgage by using one of the well-experienced specialist mortgage brokers!

These mortgage brokers are both time and cost-intensive. They help procure the kind of loan you require, maximise the potential of your current income, save big bucks on your deposit and get past the twisted credit score situation.

On top of all this, here are three ways a specialist mortgage broker will make your financial journey easier!

They tidy your complex mortgage applications.

You must think that a mortgage lender must have seen thousands of applications that display a complex case of an individual’s income. Well, that’s not true. They are usually more concerned with processing applications in bulk that fit their usual mortgage services. Most might not have ample resources to deal with unusual income structures.

This is where a specialist broker swoops in.

If you are an entrepreneur, contractor or employed professional with several sources of income, you need a specialist broker! They will understand your unconventional income portfolios and ensure that you present them to lenders in a simplistic manner. They offer you sane advice about the industry and help curate an application that fits the general standard. They also know some of the best lenders in the market who work with complex income mortgage applications.

They facilitate mortgages for non-standard constructions

Have your heart set on a property with a non-standard structure such as a pre-fabricated building, thatched roof, or a tower block? Chances are that no high street lender will come to your rescue. Your application might get rejected from the get-go.

Lenders may point out the following problems with such constructions:

  • The immense expense of maintaining the property
  • Safety hazards
  • Aggressive inspections and assessments for risk that cost both time and money
  • Insurance risks
  • Potential trouble in selling off the property in future

Some specialist mortgage brokers will offer you the right advice and help you in your unique application process.

They are familiar with lenders that specifically finance non-standard constructions and have experts that rightfully assess the risk without exaggerating the mortgage cost.

They are bound to protect you.

As a consumer, you might not be aware of all the deals in the market, which is precisely why a specialist mortgage broker is required. They are well versed with the market situation, know many lenders and can find you the most suitable mortgage deal – one you can afford.

The Australian Securities and Investments Commission (ASIC) states that if a broker goes against the consumer’s best interest, they will be liable for a civil penalty as per NCCP (National Consumer Credit Protection Act, 2009).

Thus, you can rest assured that when a specialist broker recommends a mortgage deal to you, it is most likely in your favour, devoid of any conflict of interest.

Final words

When looking to get a new property, it’s always preferable to take advice and have a specialist mortgage broker on your side.

They help with the application process, ensure that the turnaround for the same is short, and evaluate all your needs before finding the best mortgage product that aligns with your best interest.

Moreover, they possess excellent knowledge and the right contacts to help deal with a financially complex situation.

No reason why you shouldn’t get a specialist mortgage broker!

UK government explores mortgages tied to ‘green’ home improvements | Energy efficiency

UK government explores mortgages tied to ‘green’ home improvements | Energy efficiency

The federal government is checking out programs to url mortgages to green property improvements by imposing targets for loan providers, to assistance decarbonise the UK’s ageing and leaky housing stock.

Highlighting the go in its web zero strategy, revealed on Tuesday, the government mentioned it was working with mortgage creditors to aid householders in improving the power effectiveness of their homes.

Actions remaining regarded as include things like voluntary targets for banks to boost the normal strength general performance certificate rating of the households in their lending portfolio to at minimum band C by 2030.

Those targets could grow to be required “if inadequate progress” were built, according to the paperwork.

It comes as ministers weigh alternatives just after the conclusion of a consultation into the matter this 12 months.

Information of the environmentally friendly home finance loan plan, which would be a person of the most radical adjustments in the lending market place considering the fact that the 2008 economic crisis, arrive as the Uk government introduced a stream of internet-zero insurance policies in advance of the Cop26 climate summit in Glasgow this month.

Some creditors, this kind of as NatWest, have previously launched eco-friendly mortgage goods, providing a discounted interest charge on properties with an electrical power efficiency rating of A or B. Halifax also features a £250 cash-back incentive to buyers purchasing the most power productive households.

Even so, there are worries that discouraging banking companies from obtaining much less electrical power successful properties on their mortgage books would danger disadvantaging poorer customers, who could battle to boost their property’s rating.

The danger of not meeting property finance loan specifications, or becoming refused a house bank loan, could power residence buyers to invest countless numbers of lbs . on bettering their energy performance.

It could also induce a sizeable rise in “mortgage prisoners” – persons trapped in contracts and unable to secure income-preserving promotions from new loan companies refusing to consider on residences which are accountable for bigger carbon emissions.

Sarah Coles, a own finance analyst at Hargreaves Lansdown, mentioned: “The issue is that when some qualities can be enhanced at reasonably small price tag, other homeowners will find it prohibitively highly-priced.

“They may well not be able to find the money for to borrow more, or the cost of improvements to more mature attributes may be disproportionately high, so they’d never recoup the expense of the improvements by a sale.”

House owners of mentioned attributes could confront additional monetary strain, since it could be tricky to make significant modifications to historically guarded buildings.

The average cost of vitality effectiveness enhancements for a solitary residence is about £8,100, in accordance to a analyze by Nationwide Making Modern society. Nevertheless, that amount rises to £25,800 for homes with a F or G energy efficiency score.

The common yearly price savings of “greening” a household are believed at about £1,780 a calendar year, that means house owners of older properties would only begin to enjoy economic rewards right after 14 yrs.

“Greening our housing stock is important if we are to meet our weather change obligations, and financial institutions and finance vendors are dedicated to encouraging reach this objective and building sure customers are not remaining at the rear of,” stated a spokesman for the banking foyer group British isles Finance.

Information of the system arrive right after the authorities canvassed the finance industry in excess of the opportunity alterations this calendar year. The move would be portion of a generate to update as numerous households as feasible to band C scores by 2035.

“We are working with home finance loan loan companies to help home owners to improve the strength functionality of their houses and will publish our reaction to our lenders session in thanks study course,” the govt reported in its web-zero tactic printed on Tuesday.

A governing administration spokesperson stated the electricity effectiveness options “will not impede people’s potential to get a mortgage”.

They added: “We have been engaging thoroughly with a wide variety of stakeholders, which includes loan companies and customer bodies, to make certain that those people with decrease-performing homes have attractive and cost-effective options for generating inexperienced dwelling improvements.”